
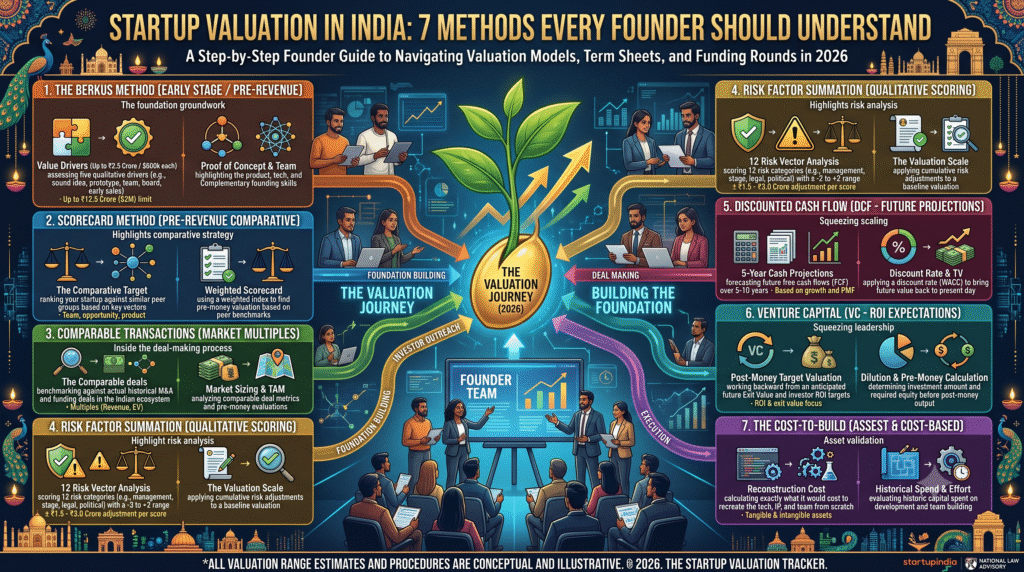
From discounted cash flow to venture capital multiples, here is how Indian founders can estimate what their startups are worth.
For startup founders, valuation is more than a number used during fundraising. It influences how much equity they give away, how investors assess their business and how they plan future funding rounds. However, valuing an early-stage startup can be challenging because revenue may be limited, profits may not yet exist, and much of the business’s potential lies in future growth.
There is no single formula that works for every company. Indian founders should understand several valuation methods before negotiating with investors.
1. Discounted Cash Flow Method
The discounted cash flow (DCF) method estimates a company’s value by calculating the present value of its expected future cash flows.
Founders prepare financial forecasts covering revenue, expenses, investments and cash generation. These projections are then discounted to reflect the time value of money and the risks associated with achieving them.
DCF is generally more useful for businesses with predictable cash flows, such as established SaaS companies or profitable businesses. For startups with uncertain forecasts, small changes in assumptions can produce dramatically different valuations.
2. Comparable Company Method
This method estimates a startup’s value by comparing it with similar businesses. Investors may examine valuation multiples such as enterprise value to revenue or price to earnings.
For example, if comparable SaaS businesses trade at a certain multiple of annual revenue, an investor may use that multiple as a reference point for a startup with similar growth, margins and customer retention.
However, founders should avoid comparing their company with much larger or more mature businesses without adjusting for differences in scale, profitability and risk.
3. Comparable Transactions Method
Instead of looking at publicly traded companies, this approach examines valuations from acquisitions or investment transactions involving similar businesses.
It can help founders understand what investors or buyers have paid for companies in the same sector. However, transaction terms, market conditions and strategic advantages can significantly affect the final price.
Because private-company deal information is often incomplete, transaction comparisons should be treated as reference points rather than exact benchmarks.
4. Venture Capital Method
The venture capital (VC) method starts with an investor’s estimate of the startup’s future value at exit. The investor then works backwards to determine how much the company could be worth today, considering the return they expect and the risk involved.
For example, if an investor expects a substantial return from an eventual acquisition or public listing, the investor may seek a larger ownership stake at the current funding round.
Founders should understand that this is an investor-orientated calculation, not a guaranteed prediction of future value.
5. Scorecard Valuation Method
Often used for early-stage startups, the scorecard method compares a business with other startups at a similar stage in the same market.
It begins with a benchmark valuation and adjusts it according to factors such as the founding team, market opportunity, product strength, competition, traction and funding requirements.
This approach is particularly useful when a startup has limited revenue and conventional financial models provide little meaningful evidence.
6. Berkus Method
The Berkus method is designed for very early-stage ventures that may not yet have significant revenue. It assigns value to qualitative milestones, which can include the strength of the idea, a working prototype, the quality of the founding team, strategic relationships and early market validation.
Its usefulness lies in assessing progress before reliable financial projections exist. However, the specific values assigned to these milestones must reflect the market and circumstances; there is no universal Indian valuation scale.
7. Revenue Multiples
Revenue multiples are widely used when assessing startups with measurable sales, particularly in software, consumer technology and subscription businesses.
A company’s estimated value may be calculated by multiplying its annual revenue by an appropriate sector multiple. That multiple depends on growth, margins, recurring revenue, customer acquisition costs and business risk.
Two startups generating the same revenue can therefore receive very different valuations.
What Indian Founders Should Remember
Valuation is a negotiation supported by evidence, not simply the highest number a founder can justify. Investors consider growth potential, market size, execution capability, competition, cash requirements and the likelihood of future returns.
Founders should maintain reliable financial records, document customer traction and understand the dilution associated with each funding round. For company-law and compliance requirements, consult the official Ministry of Corporate Affairs website. For information about recognised startup initiatives, visit Startup India.
Ultimately, the best valuation method depends on the startup’s stage, sector and available data. Using two or three methods together can provide a more balanced estimate and help founders negotiate funding terms with greater confidence.